A broad alliance of studios, unions, guilds, Jon Voight and production businesses is pressing Washington for a federal incentive. A new study outlines the potential for a substantial comeback.
By Stagerunner | September 15, 2026
For American crews, the production crisis shows up in the calendar: fewer shoot days, longer gaps between calls and another project heading overseas. This morning, a broad cross-section of the industry brought that problem to Washington with a common message: give U.S. production a more level playing field.
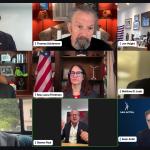
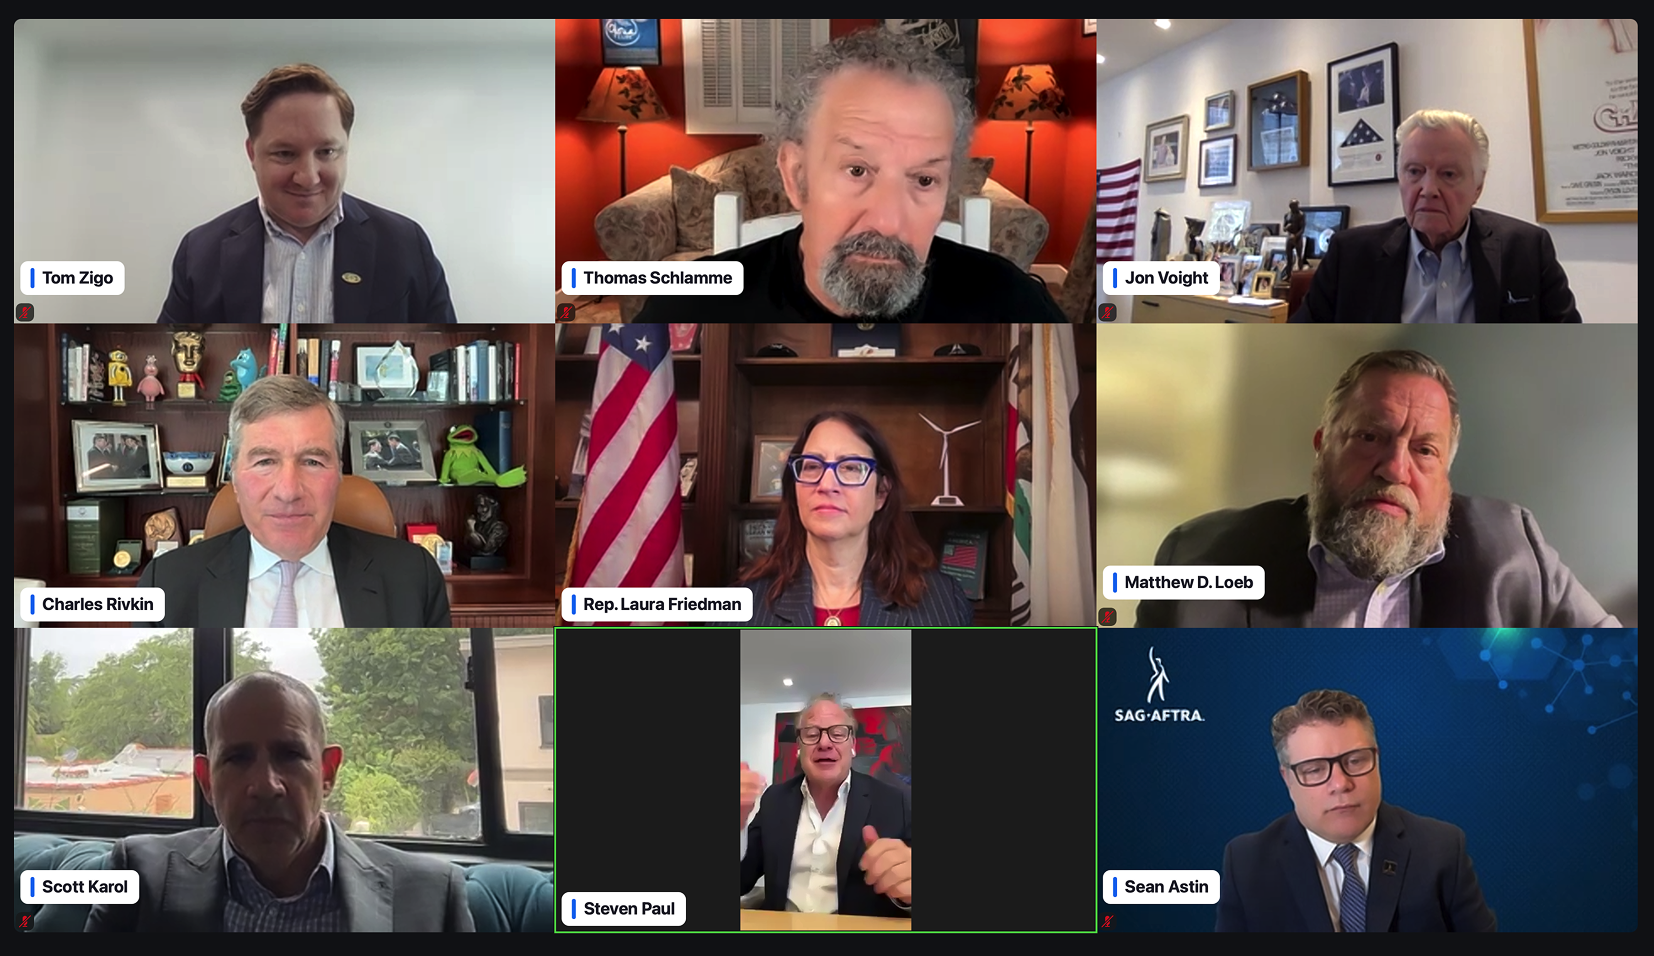
At a virtual press conference, leaders of the newly launched U.S. Film & TV Production Coalition rallied behind the bipartisan effort to establish a federal production incentive. Motion Picture Association chairman and CEO Charles Rivkin joined Hollywood special ambassador Jon Voight, Republican Rep. Brian Jack of Georgia and Democratic Rep. Laura Friedman of California, alongside the DGA’s Thomas Schlamme, IATSE’s Matthew D. Loeb, Teamsters leader Sean M. O’Brien and SAG-AFTRA president Sean Astin, according to the coalition’s announcement.
The alliance reaches well beyond the studios. Its members include national unions and guilds, the Coalition for American Production, or CAP, independent-film organizations, film commissioners and other industry groups. For a business whose employers and labor organizations frequently sit on opposite sides of the bargaining table, the breadth of that alignment is significant.
Their argument is straightforward: the United States has the people and infrastructure to compete, but individual states are being asked to compete against countries. Canada, the United Kingdom, Australia and other production hubs offer national incentives that influence where projects—and the jobs attached to them—land.
“A federal incentive would be a gamechanger for our industry,” Rivkin said in the accompanying release.
Now, the coalition is putting an economic case behind that demand.
A new study by Olsberg•SPI, commissioned by the MPA, models $249.1 billion in additional gross value added to the U.S. economy from 2027 through 2035, including $133.1 billion in labor income, and an average of 143,500 additional full-time-equivalent jobs supported annually.
Those are conditional projections, not booked productions or guaranteed hires. But they give the industry a concrete argument that the opportunity to win back work remains open
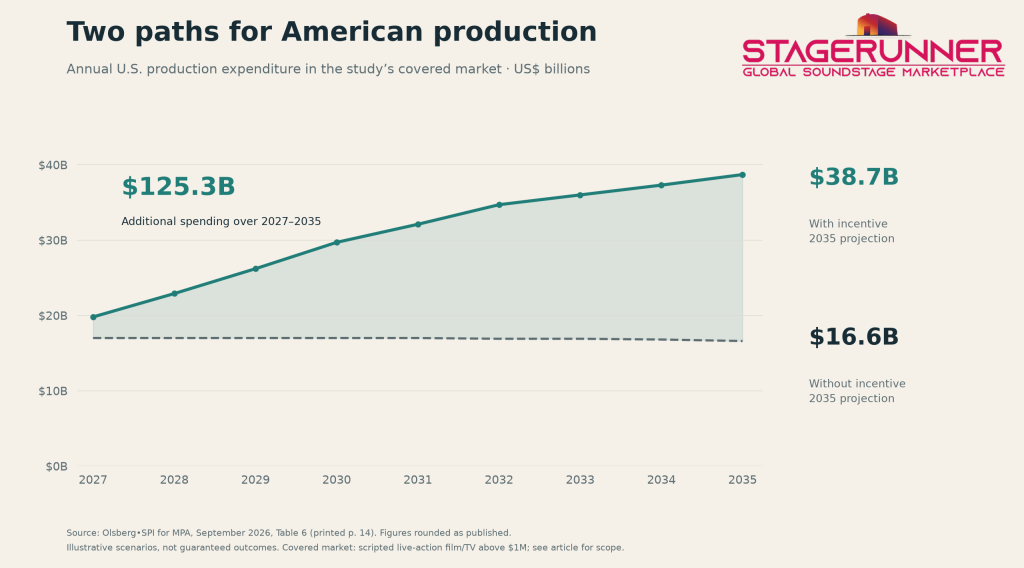
The study compares two possible paths for American production.
Without a federal incentive, annual U.S. production spending within the study’s covered market edges down from $17 billion in 2027 to $16.6 billion in 2035. With an incentive, it rises from $19.8 billion to $38.7 billion.
Across nine years, the difference totals $125.3 billion in additional production expenditure.
The market being measured matters. The analysis uses ProdPro data covering scripted, live-action film and television productions with estimated budgets above $1 million, associated with major U.S.-based distributors, platforms and channels. It is not a census of every production made worldwide.
For an equipment rental house, construction shop or catering company, however, the distinction between the two paths is practical. More domestic production means more opportunities to supply the goods, services and skilled labor a shoot requires.
That spending also travels beyond the set. Productions pay their crews and suppliers. Those suppliers support their own employees and business partners. Workers then spend their earnings in the wider economy.
SPI uses IMPLAN’s input-output framework to estimate those direct, supply-chain and household-spending effects. The projected employment benefits consequently extend beyond people working directly in film and television.
The 143,500 figure represents an annual average of additional full-time-equivalent employment across those channels. It does not mean 143,500 new permanent positions would be added every year. Similarly, the labor-income estimate includes employer compensation costs and self-employed income, rather than solely workers’ take-home wages.
These distinctions make the findings more useful: they describe the potential economic reach of production, rather than simply counting names on a call sheet.
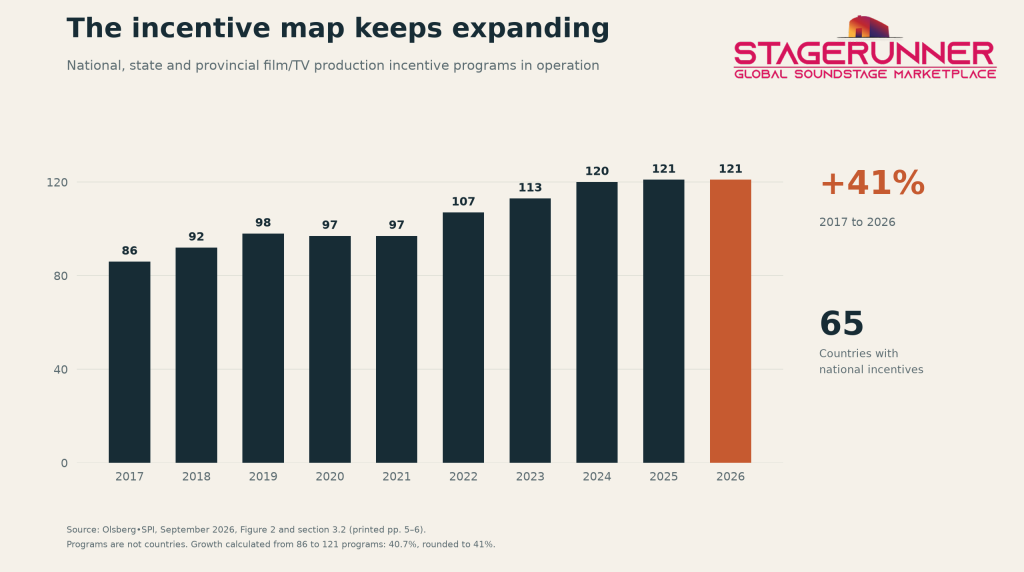
The competitive landscape has changed substantially.
SPI counts 121 national, state and provincial production incentive programs in operation in 2026, up from 86 in 2017—an increase of approximately 41 percent. The report separately identifies 65 countries with national incentives.
For the coalition, the missing federal layer is central to the problem. U.S. states have spent years building their production economies, developing infrastructure and offering incentives. But several competing markets allow producers to combine national support with regional programs.
The proposed U.S. approach would strengthen the package producers can assemble domestically. The study assumes existing state incentives remain unchanged, with a federal program operating alongside them.
That distinction matters to production communities beyond Los Angeles and New York. A federal incentive could affect location decisions across the country, including states whose existing programs cannot independently match an overseas package.
CAP executive director Brian Papworth emphasized the businesses surrounding a production in the coalition’s release, from lumber yards and paint stores to transportation companies and equipment suppliers.
It is a broader constituency than the phrase “Hollywood tax credit” suggests. Every project that moves changes the flow of orders, payroll and bookings for businesses that may never appear in the credits.
For modeling purposes, SPI assumes a transferable tax credit with a 20 percent base rate on qualifying U.S.-resident labor, a $1 million minimum spend threshold and an effective date of January 1, 2027. The assumed structure also includes five-percentage-point uplifts for qualifying labor in FEMA-declared disaster areas and for independent production companies.
Those parameters describe the proposal modeled in the study. They are not enacted law.
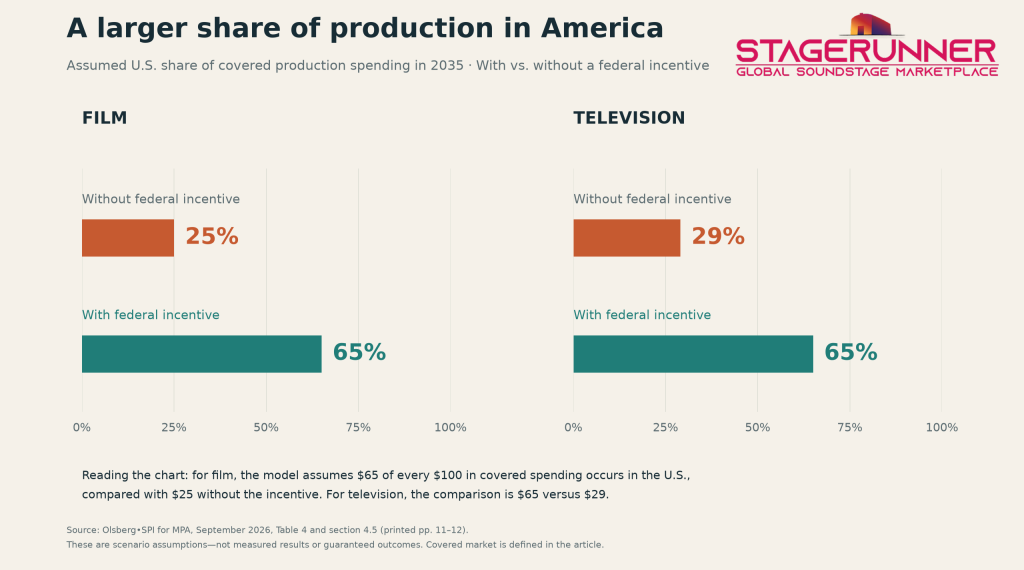
The most consequential assumption sits beneath the headline numbers: America captures 65 percent of the production spending in the study’s covered global market.
In the incentive scenario, the U.S. reaches that share for film by 2030 and television by 2032, holding those levels afterward. Without an incentive, the model assumes the shares decline to 25 percent for film and 29 percent for television by 2035.
That 65 percent figure is an illustrative assumption, not an outcome independently established by the economic model.
SPI points to historical FilmLA research and an analysis of 20 MPA member-company productions as context. In the latter sample, a 20 percent labor credit would make 16 projects competitive to produce in the United States against their overseas alternatives.
The sample supports the argument that a federal credit could materially change production economics. It does not, on its own, demonstrate that the entire covered market would reach a 65 percent U.S. share.
The study also assumes nominal global production spending grows 3.7 percent annually. Its model does not dynamically account for competing countries improving their incentives in response, constraints on available crews or facilities, or price changes as demand increases.
Nor does it evaluate alternative uses of the public funding. The $249.1 billion figure is an economic contribution estimate—not tax receipts, a federal budget saving or proof that the incentive would pay for itself. The $133.1 billion in labor income is included within that value-added figure and should not be added to it.
Those qualifications do not erase the opportunity. They identify what policymakers and the industry would need to test as a proposal becomes legislation and legislation becomes production activity.
The coalition’s challenge is to turn the competitive advantage it is seeking into measurable commitments: projects choosing American locations, crews securing sustained employment and vendors receiving the orders that keep their businesses operating.
Its unusually broad membership gives that effort political weight. Studios, organized labor, independent producers, film commissions and production suppliers have different interests, but they share a direct stake in where cameras roll.
For Stagerunner’s production community, the study’s central message is that continued decline is not the only future worth planning for. Under its assumptions, a more competitive national framework supports a meaningful expansion of American production.
The opportunity to bring work back has not been written out of the script. The next act depends on whether Washington and the producers making location decisions can turn that possibility into jobs.
Source notes: Olsberg•SPI, “Economic Impact of a Proposed US Federal Production Incentive,” September 2026, commissioned by the MPA; the September 15 coalition press release; and CAP’s September 10 statement reproduced by Creative Handbook. Conference participants and quotations are attributed to the supplied announcement. Chart 1 uses Table 6; Chart 2 uses Figure 2; Chart 3 uses Table 4 and section 4.5 of the report.